A Strategy for Reliable Monthly Retirement Income
Structured Income Flash Notes
Retirement should feel special and secure.
Structured Income Flash Notes are designed to provide monthly income linked to major market indexes — with built-in protection barrier with just a 12-month commitment.
If you're transitioning into retirement and want income that’s dependable, consistent, and with moderate to low risk, this may be worth a conversation.
Retirement changes how you think about money.
And for many investors, that unpredictability becomes harder to accept over time.
Why traditional strategies can fall short
- Real returns may be reduced by taxes and inflation
- A 60/40 portfolio still relies heavily on market performance
- Some annuities can restrict access to your capital
- Dividend income can fluctuate with market conditions
Who This May Be Right For
A Structured Income Flash Note may be worth considering if:

Predictablity
You are pivoting toward retirement and want a predictable high monthly income.
Alternative to Bonds
You want higher income potential than traditional bonds.
Defined Terms
You prefer defined one-year terms rather than open-ended market exposure.
Introducing Structured Income Flash Notes
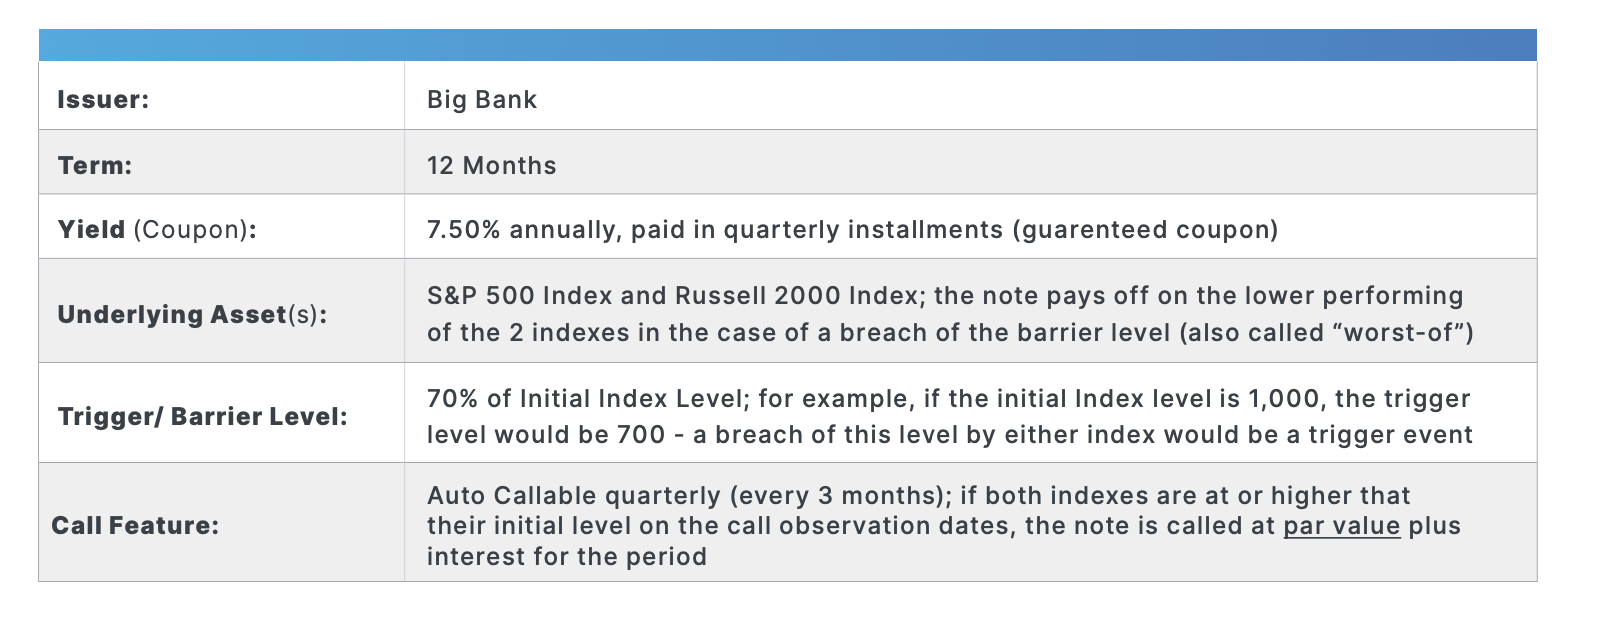
Structured Income Flash Notes are short-term debt securities linked to major stock market indexes, designed to provide defined monthly income.
- Structured income flash notes are debt securities issued by major global banks.
- They all have a 12-month term (“Flash refers to this brief duration).
- Monthly interest payments – you can spend or automatically reinvest.
- The notes are linked to three major indexes (S&P 500, Russell 2000, Nasdaq 100.
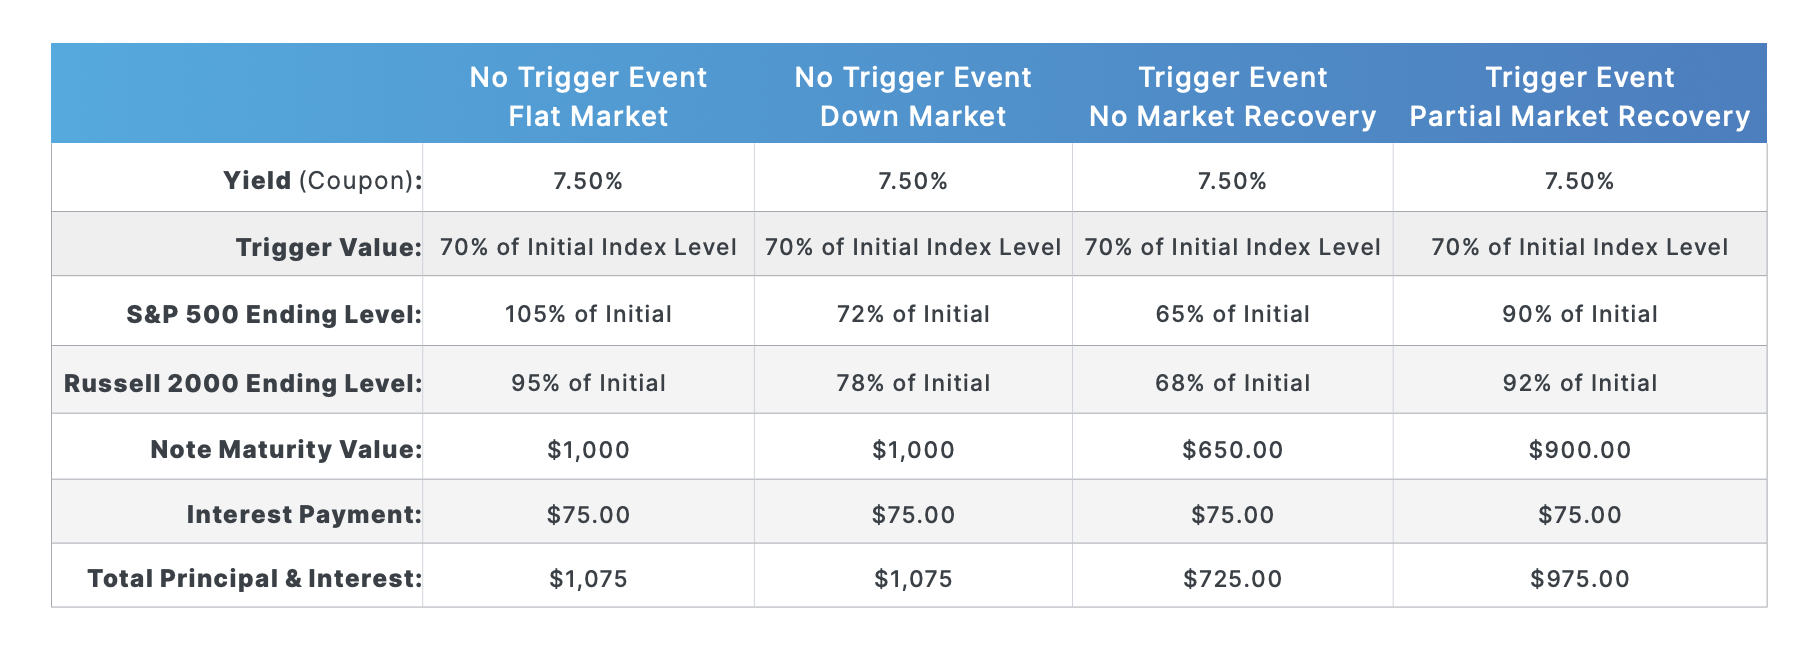
- These notes offer soft principal protection. Soft Principal protection mean that the investor's principal is protected down to a certain level (typically 30%) in an underlying asset.
Important: These are not bank deposits and are not FDIC insured. They carry the credit risk of the issuing bank and market risk beyond the protection buffer. See hypothetical example in the following page/s.
Why Haven’t You Heard of These Before?
Structured income flash notes aren’t products you can log in and buy like a mutual fund. They are negotiated directly with major banks in the capital markets, one issuance at a time.
Peter Garcia of My Legacy Group partners with Brookstone Capital Management to make these offerings available to private clients with a moderate conservative risk profile.
Are Structure Income Flash Notes right for you?
Here is a simple plan to move forward:
1. Confirm Suitability
We review your goals, timeline, and risk tolerance to determine whether this fits your broader retirement plan.
2. Structure the Account
Open an individual, joint, or IRA account and determine allocation between individual Flash Notes, the Booster Income Fund, or a blend.
3. Begin Receiving Monthly Income
Once allocated, defined interest payments begin monthly, based on the terms of each offering
Important Considerations
Structured Income Flash Notes:
- Are not FDIC insured
- Require a 12-month commitment
- Carry risk, including potential loss of principal
- Are tied to market performance and subject to issuer credit risk
They are designed for investors who understand the trade-offs and want income structured around defined terms rather than open-ended market exposure.